The card no incumbent can copy: how a startup neobank differentiates with a C-WaaS crypto offering
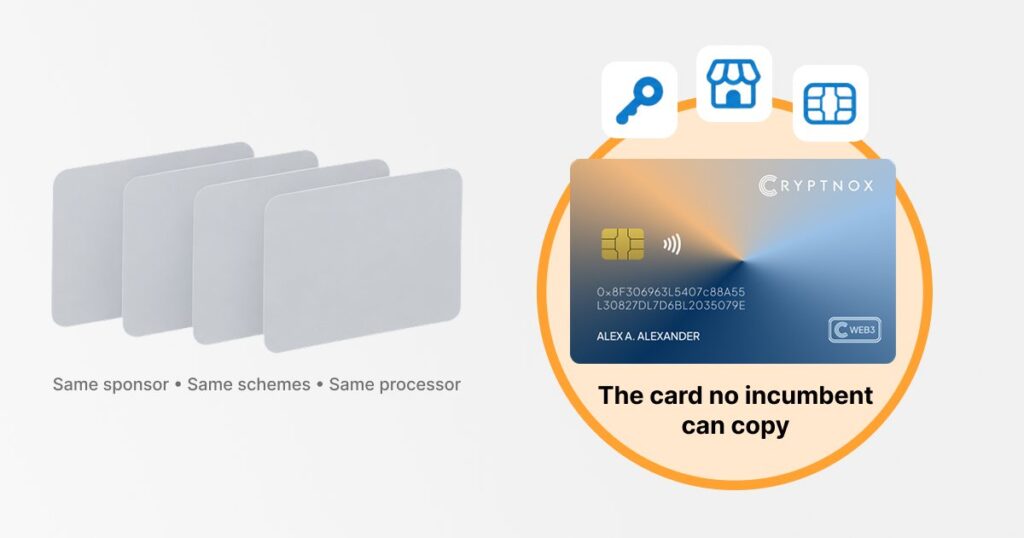
Every young bank launches with the same card from the same sponsor, the same two schemes and a processor that also serves its rivals, so the only levers left are design and price. A C-WaaS card is a feature a competitor cannot order from the same vendor: the customer's own on-chain account, on a scheme the neobank runs itself.
A startup neobank launches with the same card as everyone else. The plastic comes from the same few manufacturers, the BIN from a sponsor bank, the rails from one of two card schemes, the processing from a platform that also serves its competitors. Whatever the app looks like, the card underneath is interchangeable, and so are its economics: interchange capped by regulation, scheme fees, a fraud budget. The two levers left to differentiate on are user experience and price, and both are copied within a quarter.
This post is about the one card feature a competitor cannot order from the same vendor: a card that is also the customer's own on-chain account, issued on a scheme the neobank runs itself. It walks through what C-WaaS (Card Wallet as a Service), Cryptnox's blockchain-native card scheme infrastructure, lets a young bank offer, why no incumbent can match it by signing one more contract, and how to turn it into a launch plan. It builds on the business case for a bank, which covers what the card earns, and on the six problems a card on blockchain rails has to solve, which covers what the scheme does.
Building a neobank? Ask for the architecture brief or a demo.
The crypto options a neobank has today, and why none of them differentiates
A young bank that wants a crypto flavour has four routes, and all four lead to the same place.
The partner widget. A third-party exchange embedded in the app. The customer's assets sit at the partner, the partner owns the relationship, the price and the data, and the neobank earns a referral. Every competitor can embed the same widget next month, and several already have.
The white-label programme. A card issued by a programme manager and funded from crypto balances that the manager holds. The neobank gets its logo on somebody else's scheme membership; custody, conversion, spread and fraud sit with the provider, and so does the customer's balance. Twenty brands, one product.
The automated off-ramp card. The crypto-to-fiat debit card sold by exchanges and card programmes: a conventional card on the usual schemes, with a conversion bolted on at the back. When the customer pays, the provider sells part of the crypto balance it holds for them, and the merchant is paid in fiat through the normal rails. Every payment is a sale on the provider's venue, at the provider's spread; the balance sits in the provider's custody; interchange, scheme fees, the card number and chargebacks are all still there, because the card is a fiat card. The crypto never reaches the merchant, and the neobank is a brand on the provider's programme. A Dual-Tech C-WaaS card does the opposite: its EMV application pays in fiat where the merchant takes cards, and its C-WaaS application pays on chain, from the customer's own address, settling in the stablecoin, with no sale at the counter, no custody at a provider and no card number on the on-chain side.
Building it in-house. An exchange, a custody function, the licences for both, and the compliance stack around them. That is a different company, built over years, and it still ends with a conventional card on top.
None of the four gives the neobank a product of its own. The card stays a commodity, and the crypto feature belongs to someone else.
What makes a C-WaaS card different
C-WaaS is a complete card issuing and payment processing infrastructure with direct on-chain settlement. A bank, an issuer or a fintech runs it as its own card scheme under its own licences. Six properties matter for a neobank, because each is something the sponsor model cannot supply.
1. The card is the customer's own on-chain account. Each cardholder's funds sit at the card's own address. The payment key reaches the card through Cryptnox's patented issuance process and never leaves the chip afterwards. There is no pooled wallet on the neobank's books, so the neobank offers on-chain balances without becoming a custodian or an exchange.
2. The neobank owns the scheme. On the C-WaaS side there is no scheme between the issuer and the merchant: no interchange, no scheme fee, no BIN sponsorship. Merchant terms, the settlement asset, the venue where conversions happen and how network fees are funded are the neobank's product decisions, not lines in a rulebook it signed.
3. One card, three functions. A Dual-Tech card carries an EMV payment application for everyday spend on the networks customers expect, and the C-WaaS wallet application on the same EAL6+ certified secure element. A Triple-Tech card adds a FIDO2 security key, so the card that pays is also the card that signs the customer into the app, in place of one-time codes sent by SMS.
4. A payment path without a card number. Settlement is a plain transfer from the card's address to an approved merchant address. There is no card number to copy, so the card-not-present fraud category does not exist on these rails, and there is no chargeback after settlement.
5. Two signatures, so the issuer can approve but cannot spend. The neobank's policy engine checks every payment against limits and allow-listed destinations and signs an authorisation. That signature moves nothing. The card signs the payment itself, after verifying the authorisation and the cardholder's factor. An intrusion at the issuer yields authorisations, not funds.
6. A replacement that carries the same account. A lost card is blocked, which stops its authorisations, and the replacement card carries the same account. The customer never writes down a recovery phrase and never keeps a key on the phone.
Why a competitor cannot copy it next quarter
The sponsor model is built to sell the same product to every client. A feature inside it is, by definition, available to all of them. Four things put a C-WaaS card outside that model.
The scheme. A C-WaaS card runs on a scheme the neobank operates, under its own licences, with economics it sets. An incumbent cannot buy that from its sponsor or its processor; it would have to run a blockchain-native scheme itself.
The chip. The card is physically different: a secure element that carries the wallet application and holds the customer's key, issued through a patented process. A plastic card whose chip only runs EMV cannot be upgraded into one by a firmware update.
The relationship. The account, the identity, the card and the on-chain activity stay with the neobank. A partner widget sends the relationship and the data to the partner.
The patents. Three mechanisms at the heart of the scheme are covered by granted patents: secure key injection into the card's secure element (granted in the United States, US 12,101,400 B2), the issuance process that personalises a card without any party in the logistics chain seeing a secret (US 12,132,824 B2 in the United States, EP 4 422 119 B1 in Europe), and issuer-controlled co-signing, the rule that the issuer can approve but cannot spend (US 12,719,697 B2, granted in the United States in August 2026). A further granted patent covers key recovery (US 11,791,996 B2), and applications are pending. Patents do not make a design impossible to reproduce; they make reproducing it slow, and they mean a competitor cannot simply buy the same mechanism from another vendor. For a neobank, that is the practical point: the time a rival needs to engineer around them is time its own customers already hold the card.
| Item | Incumbent bank card | Automated off-ramp card | White-label crypto programme | C-WaaS card |
|---|---|---|---|---|
| Where the customer's funds sit | Bank deposit | In the provider's custody | At the programme manager | At the card's own on-chain address |
| What happens when the customer pays | Fiat debit through the scheme | The provider sells crypto for fiat, the merchant is paid through the scheme | Same, through the manager | On-chain transfer from the card's address; the EMV side pays fiat where needed |
| Who sets the economics | The card scheme | The provider and the scheme | The programme manager | The neobank, as scheme operator |
| Whose brand and app | The bank's | The provider's | The neobank's logo on the manager's product | The neobank's, end to end |
| Who holds the customer data | Bank and scheme | The provider | The manager | The neobank |
| Can a rival buy the same feature | Yes, same sponsor | Yes, same provider | Yes, same manager | No: the rival would have to run a scheme |
What the customer notices
Differentiation only counts if the customer can see it. Six lines a neobank can print on the tier page:
- Your key is in your card, not on a server. Nobody can drain a pool that does not exist.
- One card for the shop and for on-chain payments.
- Lost your card? Freeze it in the app; the replacement carries the same account.
- No card number to steal: nobody can pay online with your details.
- The card is your login. No codes by SMS.
- Web3 from the bank's own app, through WalletConnect and the wallets you already use.
What it does for the business
Revenue the card never had. The paid tier, network fees as a managed allowance, conversions on the neobank's own venue, merchant acceptance it prices itself and, if the neobank issues a tokenised deposit, settlement in its own asset. The business case for a bank works through each line.
Time to market. The scheme infrastructure exists. The neobank integrates its app, its identity process and its accounts. It does not build an exchange, a custody desk or smart contracts, because the scheme deploys none: cards are ordinary accounts and settlement is a plain transfer.
Regulatory posture. The cardholder's key stays in the card and the issuer holds a separate authorisation key; a payment needs both, so the issuer can approve but cannot spend, and there is no pooled hot wallet on the neobank's books. Cryptnox positions this as qualifying for self-custody treatment under EU and Swiss frameworks; the classification of a specific programme depends on who holds recovery and administrative powers in aggregate, which the operator confirms with counsel. The neobank keeps its licences and its controls.
A smaller fraud surface. No card-not-present category and no chargeback after settlement on the C-WaaS side, and a lost card replaced with the same account rather than reimbursed.
A story for the next round. An on-chain product with a physical card, operated on existing infrastructure rather than built in-house, is a product line, not a feature. It changes the conversation with investors from "another app with a card" to a scheme the company runs.
A twelve-month plan for a 50,000-customer neobank
An illustration of sequencing, not a forecast. Each step has its own regulatory and operational prerequisites.
- Months 0 to 2: pilot. Five hundred Dual-Tech cards to the customers who asked for crypto. Settlement asset chosen, limits and allow-list policy set, app integration done.
- Months 3 to 5: the paid tier. The C-WaaS card becomes the visible feature of the premium plan. Network fees run as an allowance inside the tier.
- Months 6 to 8: merchants. The neobank's own business customers enrol their terminals and are paid on chain per transaction, at an acceptance fee the neobank sets.
- Months 9 to 11: own asset, curated products. If the neobank issues a tokenised deposit, it becomes the scheme's settlement asset. The allow-list opens selected on-chain products from the app.
- Month 12: the full card. Triple-Tech cards for the premium tier, with FIDO2 login replacing SMS codes, and commercial cards for business customers on the same rails.
What C-WaaS does not do
- It is not a bank. It brings no banking licence, no fiat accounts and no fiat rails. The neobank brings those.
- It does not do identity. Verification is the neobank's process; the scheme binds a card to a verified customer.
- It is not an exchange. Conversions happen on the venue the neobank chooses.
- It does not make cards free. Issuance costs are the neobank's, as for any card programme; C-WaaS changes what the card earns, not what it costs to make.
- It is in development-environment testing today, with physical cards, virtual cards and point-of-sale terminals across six assets on four chain families. A programme's go-live depends on the neobank's integration and licences.
Sources
- Cryptnox, "C-WaaS: Blockchain-Native Card Scheme Infrastructure", "The C-WaaS business case for a bank" and "Why card-not-present fraud cannot exist on a C-WaaS card scheme" (the scheme facts quoted above).
- Regulation (EU) 2015/751 on interchange fees for card-based payment transactions: consumer interchange capped at 0.2 percent (debit) and 0.3 percent (credit), the "interchange capped by regulation" above.
- Cryptnox, "The six problems a card on blockchain rails has to solve" (key replacement, transaction checking, network-fee management, transaction health, identity binding, point of sale).
- Cryptnox, "Patented Technology": US 12,132,824 B2 (seedless initialisation and issuance), EP 4 422 119 B1 (issuance of a personalised user device, granted 14 October 2026), US 12,719,697 B2 (issuer-controlled co-signing, granted 25 August 2026), US 12,101,400 B2 (secure key injection and recovery), US 11,791,996 B2 (Shamir key recovery), EP 4 060 540 B1; pending applications listed on the same page.
Scheme facts are those published on the Cryptnox C-WaaS pages; the twelve-month plan is an illustration of sequencing, not a forecast of any programme's timeline or economics. Regulatory qualification of a specific programme depends on the issuer's jurisdiction and setup and is confirmed with counsel.